Could your family face Inheritance Tax?
Answer a few everyday questions about your home, your family and who you would leave things to. We'll estimate the tax behind the scenes—no knowledge of tax allowances needed.
No personal details are submitted or saved.
At a Glance
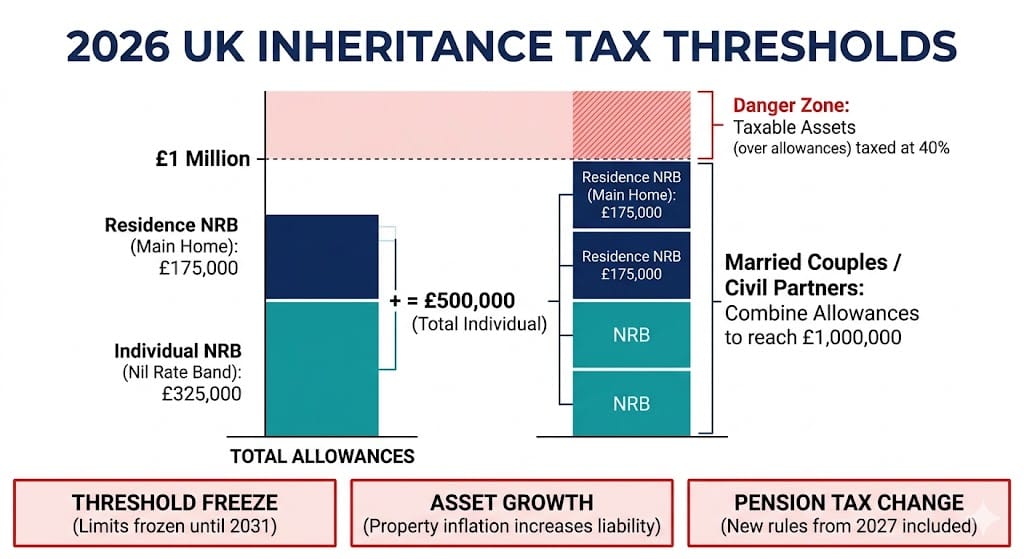
Regarding the question, "How Much is Inheritance Tax in 2026?"—most UK estates pay £0 if the total value is under £325,000. However, for homeowners leaving property to direct heirs, you can pass on up to £500,000 (individuals) or £1 Million (married couples) before the 40% tax rate applies. In 2026, the real risk is "Fiscal Drag," as frozen thresholds mean more families are being hit by tax bills as house prices rise.
How much is Inheritance Tax in 2026? Thresholds, Tapers, and the £2M Cliff
Quick Answer: In 2026, the standard Inheritance Tax rate is 40%. However, most families utilise a combination of the Nil Rate Band (£325,000) and the Residence Nil Rate Band (£175,000) to create a tax-free threshold of £500,000 per person, or £1 Million per married couple. Understanding exactly how much is Inheritance Tax for your specific estate requires looking at the "Taper Cliff" and the downsizing rules.
How the allowances work together
Non-exempt lifetime gifts generally use the standard nil-rate band before the estate. The residence nil-rate band is a separate allowance for a qualifying home passing to direct descendants; it cannot shelter lifetime gifts. See the gifting examples below for how taper relief affects tax on gifts.
- Standard nil-rate band: Normally £325,000. A surviving spouse or civil partner can claim the unused percentage of a late partner's band, potentially increasing it to £650,000. Earlier gifts and other transfers may reduce the unused percentage.
- Residence nil-rate band: Up to £175,000, limited by the qualifying home interest inherited by direct descendants and the estate-size taper. A separate claim may transfer unused residence allowance from a late spouse or civil partner.
- Downsizing addition: Selling or downsizing a former home on or after 8 July 2015 can preserve some or all of the residence allowance if the statutory conditions are met, including assets passing to direct descendants. It is not an extra allowance on top of the maximum residence band.
The £2 million residence allowance taper
The residence allowance reduces by £1 for every £2 that the estate exceeds £2 million. This test uses the estate after allowable debts but before spouse or charity exemptions and agricultural or business relief. Business relief therefore does not itself bring an estate below this taper threshold. Trust interests require individual assessment.
With one full £175,000 residence allowance, it is exhausted at £2.35 million. With a full combined £350,000 allowance, it is exhausted at £2.7 million. A 60% marginal tax effect can arise while the allowance is being withdrawn where the additional value is otherwise taxed at 40%; this is not a 60% rate on the whole estate.
See HMRC guidance on the residence allowance and taper.
When the 36% charity rate can apply
A qualifying charitable legacy of at least 10% of the statutory baseline amount can reduce the rate to 36% on the relevant estate component. The baseline is a technical calculation, and the reduced rate does not necessarily apply to every asset. A charitable gift reduces what is available to other beneficiaries; do not assume that it leaves the family better off than making no charitable gift. Obtain a calculation for the actual estate.
See GOV.UK guidance on Inheritance Tax rates.
Stop Guessing. Start Protecting.
Our 2026 IHT Audit provides a precise calculation of your thresholds, tapers, and potential savings.
→ Get Your Bespoke 2026 AuditWhy are more families paying IHT in 2026? The "Fiscal Drag" Trap
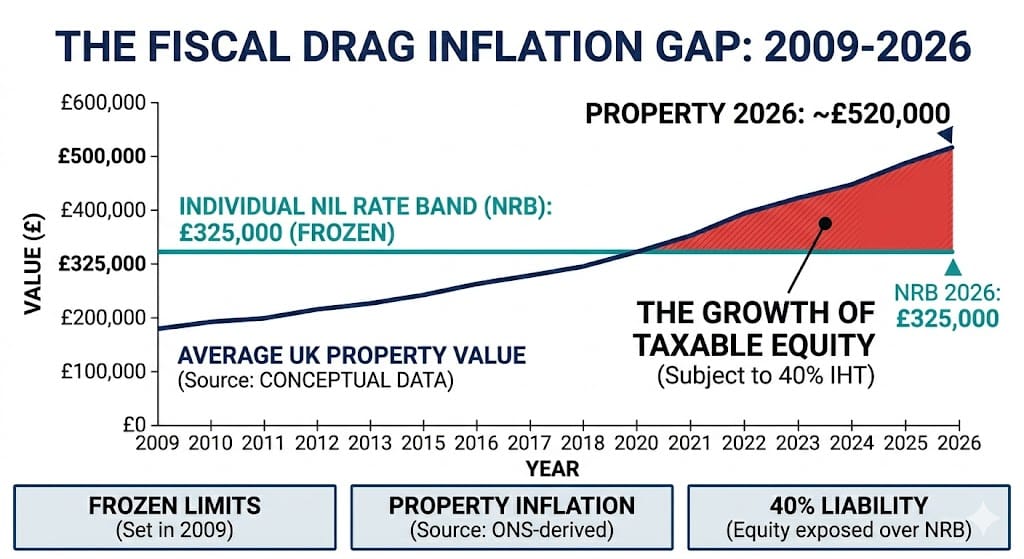
The Short Answer: Even though the 40% rate hasn't changed, how much is Inheritance Tax in 2026 has increased because the tax-free thresholds have been frozen while property and asset values have soared. This "Fiscal Drag" quietly pulls thousands of modest family estates into the tax bracket every year.
The 2009 vs. 2026 Comparison
The standard Nil Rate Band (£325,000) has been fixed since 2009. To maintain the same "purchasing power" and shield the same percentage of a family's wealth, that threshold should technically be over £520,000 today based on Consumer Price Index (CPI) data.
By maintaining the freeze until 2031, the government is executing a "stealth tax." As inflation devalues the pound, the real-terms value of your tax-free allowance shrinks, leaving a larger portion of your family home, savings, and investments exposed to the 40% HMRC charge.
The Liquidity Risk for Homeowners
This phenomenon creates a severe liquidity crisis for beneficiaries. Because IHT is calculated on the total estate value but must often be paid before Probate is granted, families find themselves with a massive cash liability tied up in a property they cannot yet sell.
The 2026 Liquidity Warning: In high-growth areas, "average" homes now routinely push estates past the £1 Million threshold. Because IHT must be settled before Probate is granted, many families face a "Cash Gap."
Without a Discretionary Trust Will to create deductible estate debts—or life insurance written in Trust to provide immediate liquidity—your heirs may be forced into high-interest "Probate Loans" just to satisfy HMRC before they can access the property's value.
Inheritance Tax information and payment issues can also affect the progress of an application. If a grant is taking longer than expected, read our guide to tracking a probate application .
Are pensions subject to Inheritance Tax? The 2027 "Double Tax" Reform
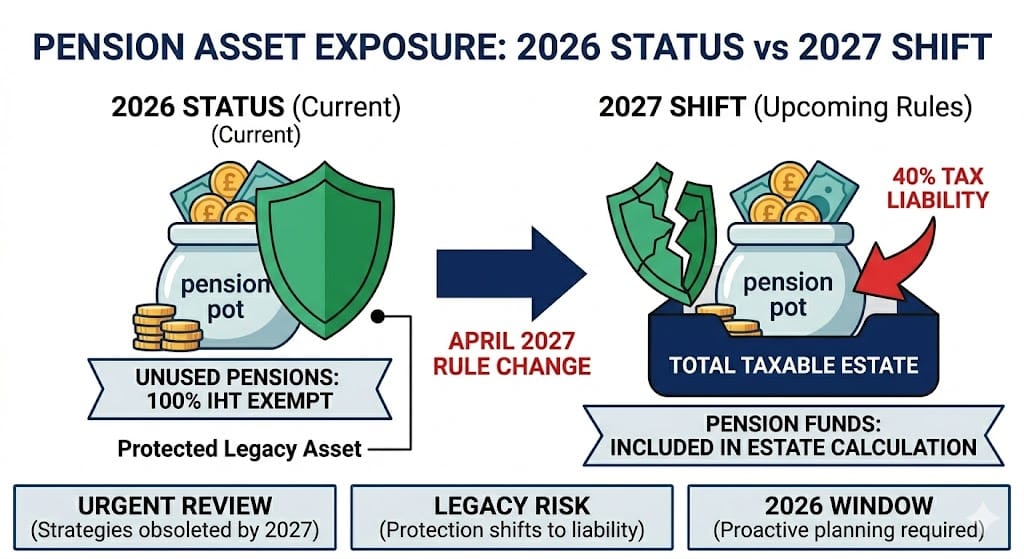
The Short Answer: Currently, in 2026, most unused pension pots remain exempt from Inheritance Tax. However, from April 2027, the UK government will bring unused pension funds into the value of your estate, exposing them to the 40% tax rate. This represents the most significant shift in how much is Inheritance Tax for the average family in decades.
The "Double Taxation" Risk
The 2027 reform creates a complex tax trap. Not only will the pension pot be subject to 40% Inheritance Tax upon death, but if the deceased was over age 75, the beneficiary will also pay Income Tax at their marginal rate on any withdrawals.
Example: For a £100,000 pension pot left to a high-earning child, IHT takes £40,000. If the child then withdraws the remaining £60,000 as a 40% taxpayer, they lose another £24,000. The effective tax rate on that retirement legacy is a staggering 64%.
Why your "Expression of Wish" is no longer enough
Historically, pensions bypassed probate because they were held "outside the estate" at the discretion of the pension trustees. With the 2027 inclusion, the simple nomination forms you signed years ago may now inadvertently trigger a massive tax bill. To protect the legacy, you must determine how much is Inheritance Tax based on your *total* asset pool, including SIPP and personal pension valuations.
The 2026 Strategy Window:
By reviewing your Trust structures and retirement drawdown strategy in 2026, you can potentially move funds or change your spending habits to reduce the estate's value before the 2027 "inclusion date." Waiting until the rules change could be an incredibly expensive mistake.
How can I legally reduce my IHT bill? Gifting and Insurance Strategies
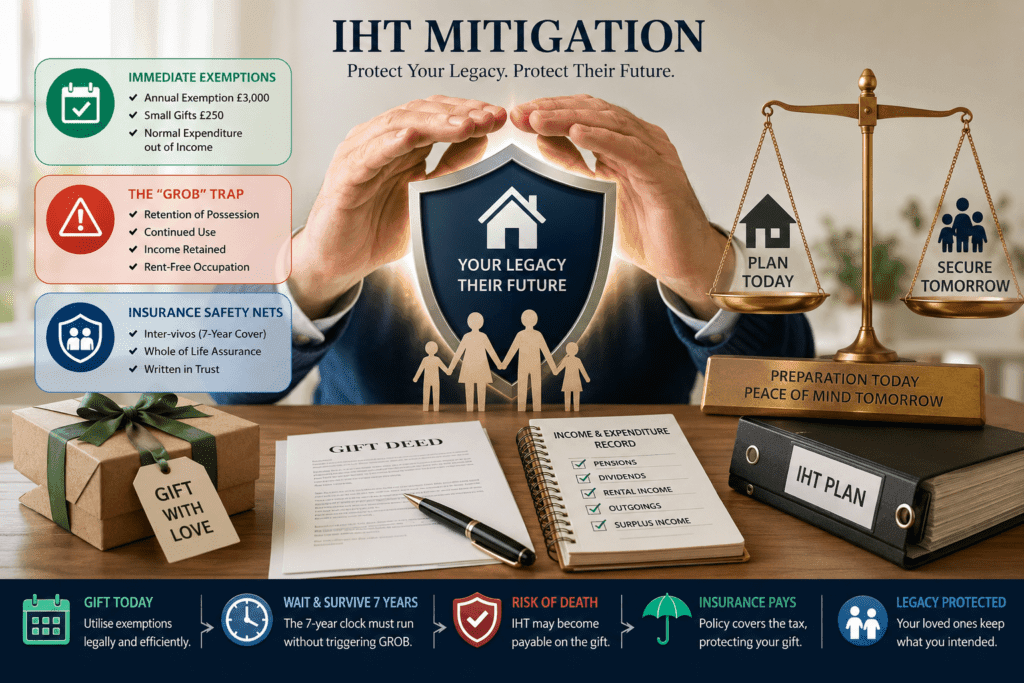
The Short Answer: You can reduce how much is Inheritance Tax by using immediate exemptions (like the £3,000 annual gift), making regular gifts from surplus income, or utilizing "Potentially Exempt Transfers" (PETs) which leave your estate entirely after seven years. For large, immediate gifts, many homeowners use Inter-vivos insurance to cover the tax risk during that 7-year window.
1. Immediate Exemptions (The "No-Wait" Clauses)
Certain gifts leave your estate instantly, meaning they do not count toward the calculation of how much is Inheritance Tax due on your death:
- The Annual Exemption: Every individual can gift £3,000 per tax year. Unused allowance from the previous year can be carried forward, allowing a couple to potentially remove £12,000 from their estate in a single day.
- Small Gift Allowance: Unlimited gifts up to £250 per person (provided they haven't received part of your £3,000 allowance).
- Normal Expenditure out of Income: The most powerful exemption. Regular gifts made from demonstrable surplus income that do not impact your lifestyle are exempt from IHT immediately.
⚠️ THE COMPLIANCE BURDEN:
HMRC requires rigorous proof of "surplus." If you dip into capital or savings to fund these gifts, HMRC will reclassify them as taxable, drastically changing the math on how much is Inheritance Tax your family will eventually pay.
How gift taper relief works: allowances first, tax reduction second
In plain English: taper relief is a discount on tax that is actually due on a lifetime gift after death. It is not a discount on the gift itself. First identify the non-exempt gifts and the available standard allowance; only then apply the time-based reduction to any gift tax.
Most outright gifts to individuals are potentially exempt transfers (PETs). If the donor survives seven years, they normally fall outside the Inheritance Tax calculation (provided there is no gift with reservation of benefit). If the donor dies sooner, non-exempt gifts made in the seven years before death are brought back into the calculation, usually in date order, oldest first.
Step 1 — use the standard nil-rate band. After allowing for any relevant gifting exemptions, earlier non-exempt gifts generally use the donor's £325,000 standard nil-rate band first. Any of that band used by gifts is not then available to set against the estate on death. Earlier chargeable transfers, including certain transfers into trust, can complicate this calculation.
Step 2 — check whether a gift itself becomes taxable. A gift, or the part of a gift, that exceeds the unused standard nil-rate band may create tax payable on the gift following death. Taper relief reduces that tax on the taxable gift if the donor survived more than three years after making it. It does not reduce the gift's value, restore the nil-rate band, or reduce the tax due on the remaining estate simply because time has passed.
| Time between gift and death | Effective rate on taxable part of gift* |
|---|---|
| Under 3 years | 40% |
| 3–4 years | 32% |
| 4–5 years | 24% |
| 5–6 years | 16% |
| 6–7 years | 8% |
| 7 years or more | Generally exempt |
*These are the effective rates after taper relief, assuming the normal 40% death rate and that the relevant portion of the gift is taxable. A gift entirely within the available nil-rate band pays no gift tax, so there is nothing for taper relief to reduce.
Example 1: a £250,000 gift towards a house deposit
Suppose a grandmother gives £250,000 to a grandchild, with no earlier transfers using her standard nil-rate band and ignoring the annual gifting exemption for simplicity. If she dies two years later, the gift itself normally attracts £0 IHT: it falls within £325,000. However, it uses £250,000 of that allowance, leaving just £75,000 of her standard nil-rate band for the estate. If she dies five years after the gift instead, the result is still £0 tax on the gift and £75,000 of her standard nil-rate band for the estate. There is no taper relief on this gift because no gift tax arose.
Example 2: a £400,000 gift where taper relief does apply
Assume instead that she makes an outright £400,000 gift, with no earlier relevant gifts and no exemptions for this illustration. The first £325,000 uses her nil-rate band; £75,000 exceeds it. If she dies within three years, tax on that excess could be £30,000 (40% of £75,000). If she dies between four and five years later, gift tax could be £18,000 (24% of £75,000). In either case, the gift still uses the full standard nil-rate band; taper relief reduces the tax on the £75,000 taxable part of the gift, not the amount charged against the allowance.
Example 3: the gift tax and estate tax are separate
Suppose the £400,000 gift above was made four years and six months before death, and the grandmother leaves a further £200,000 estate to a friend. Assume a £325,000 standard band, no transferred allowance, no residence allowance, no exemptions, reliefs or earlier transfers. Gift tax is £18,000 after taper relief. The gift has already used the whole standard band, so the remaining £200,000 estate is taxed at 40%: £80,000. The combined illustrative liability is £98,000. The estate tax does not fall to 24% just because the gift qualifies for taper relief.
Two different tapers: gifts and the residence allowance
Gift taper relief depends on the time between a taxable lifetime gift and death and reduces tax on that gift. Residence nil-rate band tapering depends on estate size above £2 million and reduces an allowance. They are separate rules: the residence allowance cannot be set against lifetime gifts.
How does the residence nil-rate band fit in?
The additional residence nil-rate band (normally up to £175,000 per qualifying individual) is a separate estate allowance where a qualifying residential interest passes to direct descendants and the other conditions are met. It cannot be used to shelter lifetime gifts that exceed the £325,000 standard nil-rate band. For qualifying estates worth more than £2 million, the residence allowance is reduced by £1 for every £2 above that threshold, potentially removing it entirely. The inheritance and ownership arrangements matter.
Marriage alone does not double the gift allowance. However, on the surviving spouse or civil partner's death, a valid claim for an unused standard nil-rate band from a late partner can increase the band used in the death calculation, including lifetime gifts that become chargeable because of that death. A fully transferred standard band can therefore change whether the gifts themselves attract tax and whether taper relief has any tax to reduce. This differs from an immediately chargeable lifetime trust transfer: the transferred band cannot cover the initial lifetime entry charge. The separate residence allowance still cannot cover lifetime gifts. See HMRC on transferred allowances and lifetime transfers.
Gifts with reservation of benefit, trust transfers, exemptions, the interaction of earlier transfers and who is liable for tax can change these examples. A seven-year inter-vivos policy should only be considered after identifying the actual potential tax liability; it does not automatically pay HMRC or protect an estate.
Primary sources: HMRC: work out tax due on gifts, GOV.UK: gifts and the seven-year rule and HMRC: residence nil-rate band.
How does the new 2026 Business Property Relief (BPR) cap work?
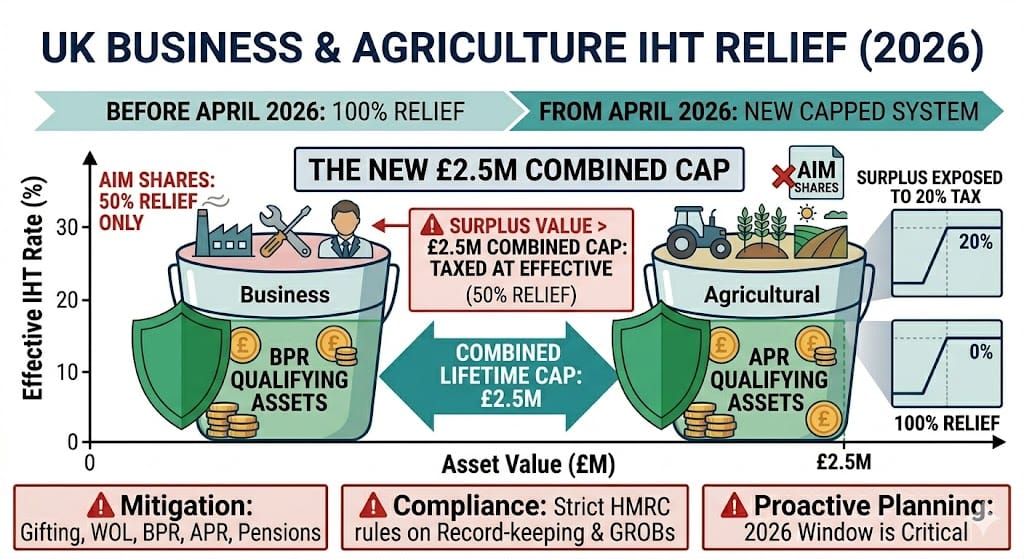
The Short Answer: As of 6 April 2026, 100% relief for business and agricultural assets is capped at a combined £2.5 Million per estate. For value exceeding this cap, relief is reduced to 50%, resulting in an effective tax rate of 20% on the surplus. Understanding how much is Inheritance Tax for business owners now requires calculating this tiered relief across trading assets and AIM portfolios.
The £2.5 Million Allowance: Allocation and Prioritisation
The new cap applies to the aggregate value of all business (BPR) and agricultural (APR) assets. If your estate holds both, HMRC requires you to allocate the £2.5M allowance proportionally across those assets.
For married couples, the transferability of this allowance is the cornerstone of 2026 planning. By properly structuring Wills and Trusts , a surviving spouse can utilize a combined £5 Million exemption. However, failing to use the first spouse's allowance at the point of death could lead to it being "swallowed up" by other assets, effectively wasting a £1 Million tax saving.
Calculating the "Surplus Value" Tax: The 20% Effective Rate
Under the new rules, value above the £2.5M cap receives 50% relief. Because the standard IHT rate is 40%, applying it to only half the value creates a 20% liability.
Mathematical Case Study (Family Farm/Business):
- Estate Value: £8 Million in trading assets.
- First £2.5M: 100% Relief (£0 Tax).
- Surplus £5.5M: 50% Relief (£2.75M remains taxable).
- Final Bill: 40% of £2.75M = £1.1 Million Tax Liability.
This creates a massive liquidity crisis. Without a Whole of Life insurance policy written in Trust, heirs may be forced to sell land or divest parts of the business to pay HMRC within the 6-month deadline.
Technical Pitfalls: "Binding Contracts" and AIM Portfolios
- The "Binding Contract" Trap: Partnership agreements that force a buy-back of shares upon death disqualify the asset from BPR entirely. To protect the relief, agreements must use "Cross-Option" clauses.
- The 2-Year Rule: Assets must be owned for two years prior to death. Moving "deathbed" cash into a business is an immediate red flag for HMRC audit.
- AIM Portfolio Restriction: As of 2026, Alternative Investment Market (AIM) shares are excluded from the 100% relief bracket. They are capped at 50% relief from the first £1, making them a much higher risk for IHT planning than in 2025.
Inheritance Tax vs. Care Fees: Which is the bigger threat to your estate?
The Short Answer: While homeowners often prioritize how much is Inheritance Tax, Social Care fees represent a more aggressive threat. While IHT is a one-time 40% charge on surplus wealth, care fees are an ongoing 100% liability that can consume nearly your entire estate, leaving only a statutory "safety net" of £23,250 in England or £50,000 in Wales.
The "Deliberate Deprivation" Conflict
In 2026, a common error is gifting assets to reduce how much is Inheritance Tax without considering local authority "look-back" powers. If a gift is deemed to have been made with the "significant expectation" of care needs, it is reclassified as Deliberate Deprivation of Assets.
Unlike the 7-year rule for IHT, there is no time limit for care fee assessments. A local authority can legally assess your finances as if you still owned a property transferred years prior, potentially leaving your family with a massive bill and no remaining assets to settle it.
| Liability Metric | Inheritance Tax (IHT) | Care Fees (England) | Care Fees (Wales) |
|---|---|---|---|
| Upper Capital Limit | £325k - £1m+ (Thresholds) | £23,250 | £50,000 |
| "Partial Funding" Zone | N/A | £14,250 - £23,250 | N/A (Full help below £50k) |
| The Family Home | RNRB Protection (£175k) | Exposed if living alone | Exposed if living alone |
| Gifting Constraints | 7-Year Rule (PETs) | No Statutory Time Limit | No Statutory Time Limit |
The Statutory Property Disregard & Trust Protection
While care rules are aggressive, the Mandatory Property Disregard offers a vital shield. Your home is not counted in a financial assessment if it is still occupied by a spouse, a partner, or a relative over 60. By utilising Life Interest Trusts in 2026, the trust terms can provide for the surviving spouse while preserving the underlying capital for chosen beneficiaries. The Inheritance Tax and care-funding consequences depend on the structure and circumstances and should be considered separately.
Related Guide: Are Next of Kin Responsible for Care Home Fees in 2026?
Protect Your Estate for the Next Generation
The 2026 landscape of frozen tax bands, pension reforms, and care fee liabilities is a minefield. Professional estate planning ensures your hard-earned assets go to your children, not the State.
Book Your Comprehensive 2026 Estate ReviewTell us what you want to achieve
You do not need to know the name of the legal document or trust before speaking to us. Explain the family, property or planning issue and we can discuss the relevant options.
Have a question before booking? Send us a short message and we’ll respond personally.