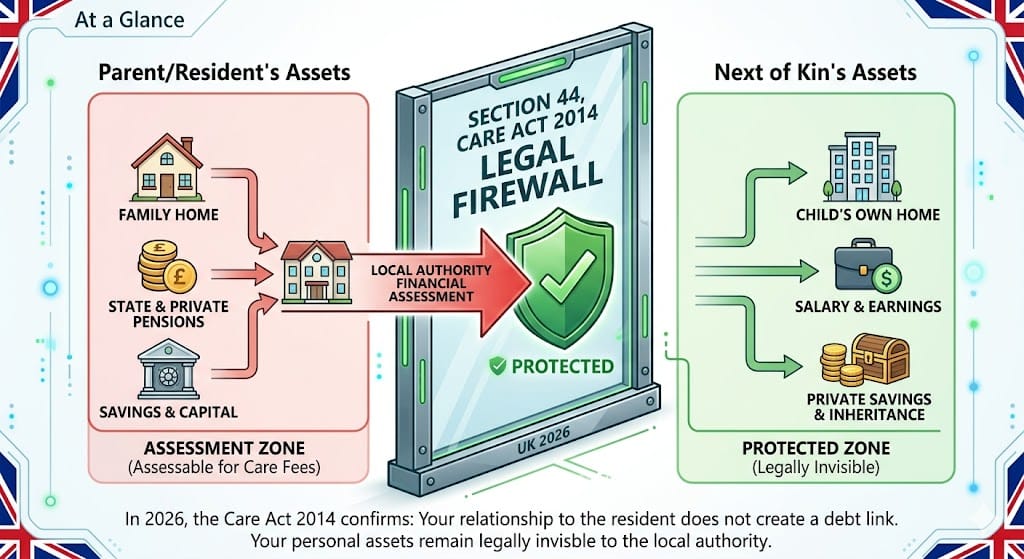
At a Glance
Regarding the question, "Are Next of Kin Responsible for Care Home Fees?"—the answer in 2026 is No. Under the Care Act 2014, next of kin are not legally liable for a relative's care costs in the UK. A relative is not personally liable simply because they are next of kin. The treatment of the person receiving care’s own home and other assets depends on the Care Act charging rules, applicable disregards, ownership and individual circumstances.
Are Next of Kin Responsible for Care Home Fees?
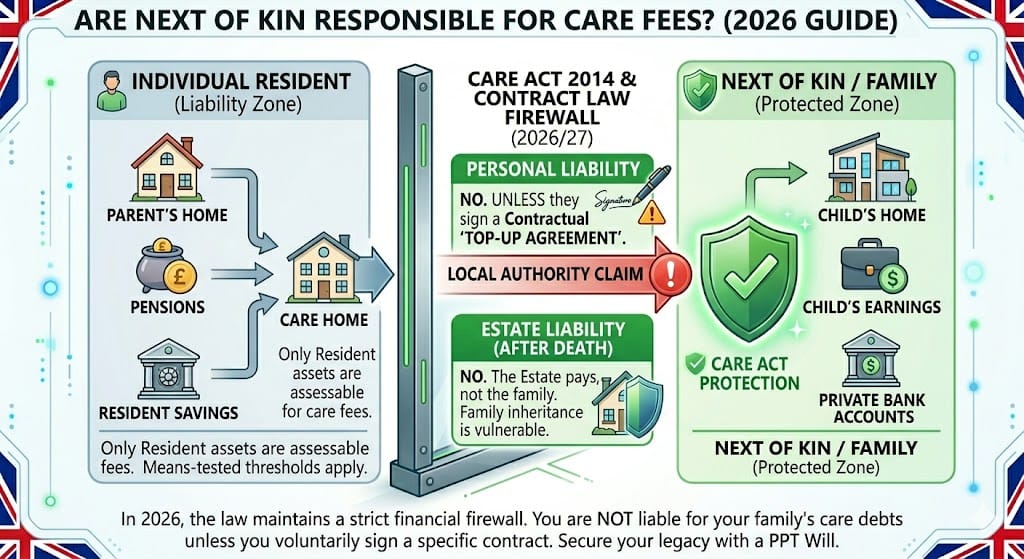
One of the most common concerns for UK families in 2026 is: Are Next of Kin Responsible for Care Home Fees? The short answer for any child, spouse, or relative is No. Under the Care Act 2014, next of kin have zero legal liability for a family member’s care costs; UK law treats every adult as a separate financial entity.
When a local authority conducts a financial assessment, they are legally restricted to looking only at the assets and income of the person receiving care. Your savings, your property, and your salary are entirely exempt from their calculations.
The 2026 Legal Reality:
Even if you are the primary "Next of Kin" or hold Lasting Power of Attorney, you are an administrator, not a guarantor. You are responsible for managing their funds, but the council cannot force you to spend your own money when addressing care home fees responsibility.
Legal Verification & Sources:
- Care Debt Recovery: Section 69, Care Act 2014 (Local Authority Powers).
- NHS Funding: National Framework for NHS CHC (2026 update).
- Property Trusts: Digital Assets (Property) Bill & Land Registry Guidance.
What the Council Cannot Assess:
- Child’s earnings: a relative’s own salary is not automatically treated as the care recipient’s income merely because they are next of kin.
- Next of kin’s property: a relative’s separately owned home is not automatically treated as the care recipient’s capital merely because of the family relationship.
- Private savings: a relative’s separately owned savings are not automatically treated as the care recipient’s capital merely because they are next of kin.
What is the "Third-Party Top-Up" Trap?
Being next of kin does not itself make you liable for another adult’s care charges. However, a person can take on a separate contractual payment obligation—for example by entering into a third-party top-up agreement—so the terms should be understood before signing.
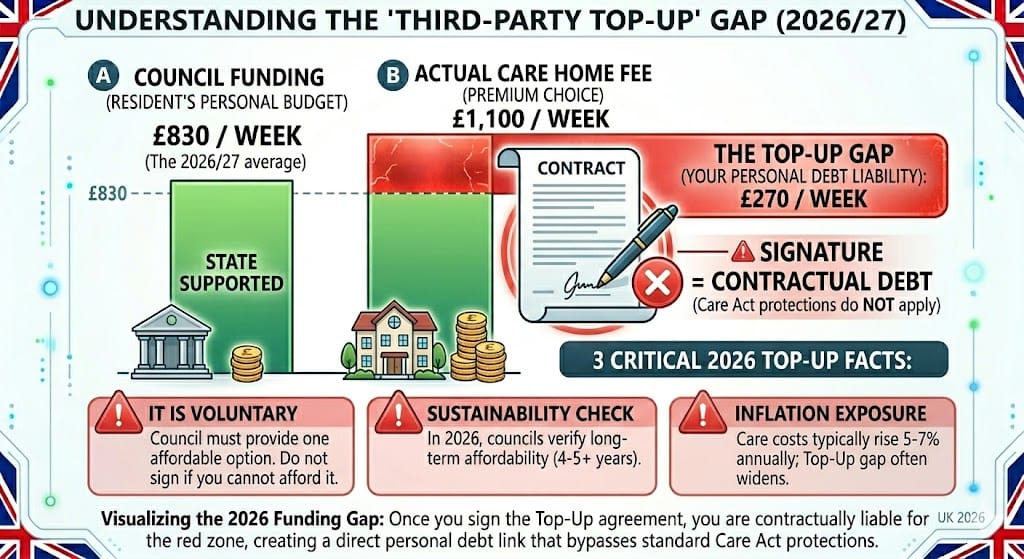
If the local authority assesses a resident's "Personal Budget" at £830 per week, but you prefer a care home that costs £1,100, the council will ask you to sign an agreement to pay the £270 difference. Once signed, this is a legally binding private contract where you accept personal liability.
The 2026 Risk Warning:
A third-party top-up agreement can create a contractual payment obligation for the person who signs it. The amount and review arrangements depend on the agreement, so affordability and potential future increases should be considered before committing.
3 Critical Facts Before You Sign:
- It is Voluntary: The council must provide at least one affordable care home option. You only pay a Top-Up if you reject that option.
- Sustainability Check: In 2026, councils must verify you can afford these payments long-term.
- Inflation Exposure: You are responsible for the gap. As care costs rise, the gap usually widens.
Who pays the debt after death?
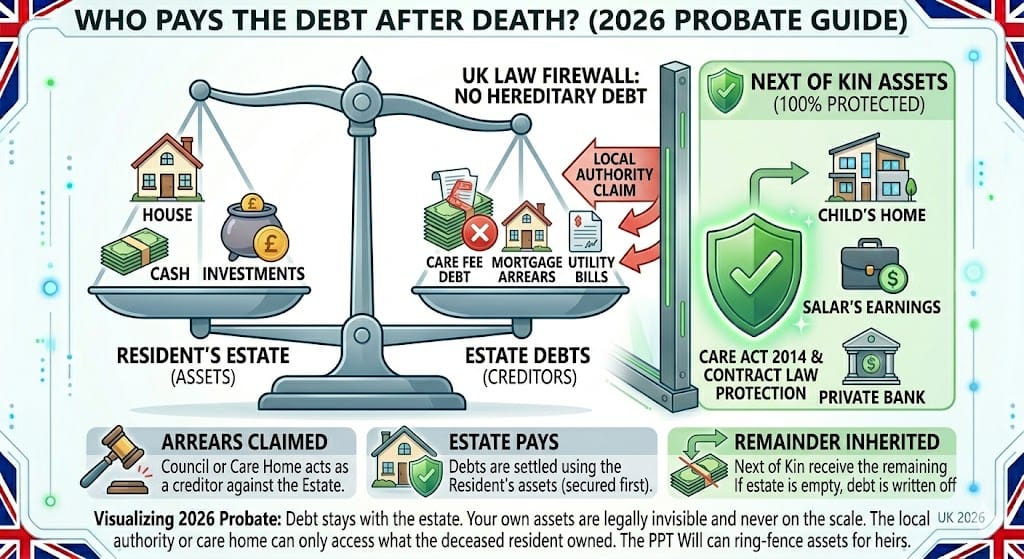
One of the most persistent fears for next of kin is the idea of "inheriting" a care fee debt. In the UK, debt is not hereditary. If a resident passes away with outstanding care home fees, the debt belongs to the estate, not to the children.
In 2026, the local authority or the care home acts as a creditor. They will seek payment from the deceased’s assets (money, property, or investments). If the estate has no assets left, the debt usually remains unpaid and is eventually written off. The council cannot legally demand that a child pay a parent’s debt from their own pocket.
The Probate Connection:
As the executor, you must ensure all debts are settled before distributing inheritance. If you distribute the estate to yourself or siblings while knowing a care debt exists, you could become personally liable for that oversight. This is why tracking a probate application correctly is vital.
The Hierarchy of Payment (2026 Rules)
- 1. Secured Debts: Any "Deferred Payment Agreements" (where the council put a charge on the house) are paid first upon sale.
- 2. Unsecured Care Arrears: These are settled from the remaining cash in the estate.
- 3. The Heirs: Next of kin receive whatever is left after all creditors are satisfied.
If a deceased owner’s share of a property passes into a valid Will trust, ownership of that share is governed by the trust terms rather than an outright gift to the survivor. Whether and how any asset is relevant to debts, estate administration or a later care-funding assessment depends on the legal ownership and the individual facts; no blanket creditor or care-fee exemption should be assumed.
How Do I Protect the Family Home?
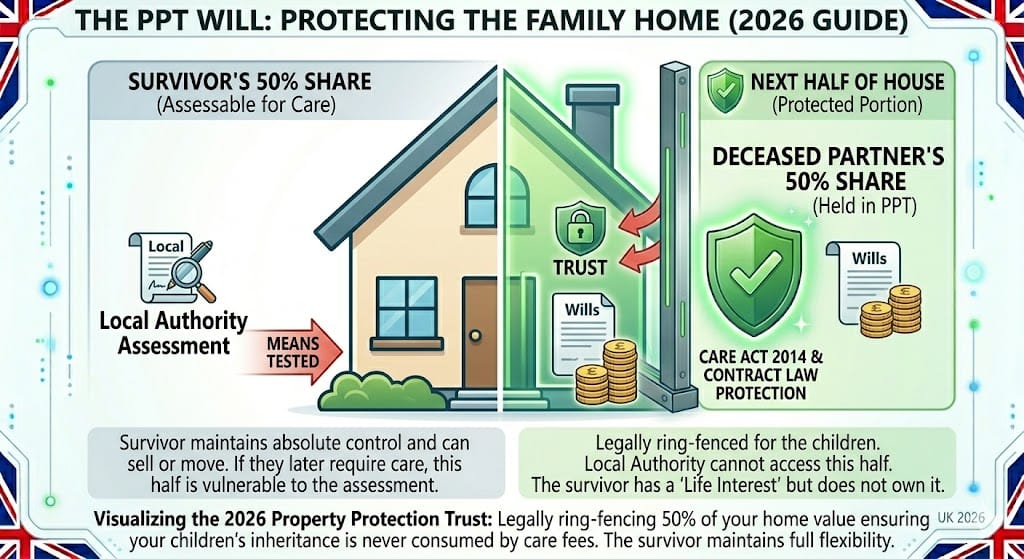
For homeowners, estate planning may include reviewing joint ownership, Wills and whether a Will trust is appropriate for succession objectives. A Property Protection Trust Will can preserve a deceased owner’s share for chosen beneficiaries while giving the survivor rights under the trust, but it is not a guaranteed method of avoiding future care charges.
Joint tenants and tenants in common have different succession consequences. As tenants in common, each owner can have a distinct share capable of passing under their Will. That can support Will-trust planning, but changing the ownership structure does not by itself determine the outcome of a future care-funding assessment.
The 2026 Strategy:
Where a Will trust applies to the first owner’s share, the survivor may have rights to occupy or benefit from the trust property without owning the deceased owner’s trust share outright. Any later financial assessment depends on the legal ownership, trust terms and individual circumstances; it should not be described as an automatic 50/50 care-fee exclusion.
3 Key Benefits of a PPT Will:
- Succession control: the trust can preserve the deceased owner’s share for the beneficiaries subject to the trust terms, rather than passing that share outright to the survivor.
- ➔ Security: Protects your children's inheritance even if the surviving spouse remarries.
- ➔ Flexibility: The survivor can still sell the house to downsize; the Trust simply moves to the new property.
What is the 2026 Protection Bundle?
A coordinated plan can bring together Wills, property ownership and LPAs so that succession and lifetime decision-making are considered together. It does not guarantee a particular care-fee assessment, creditor outcome or inheritance value.
1. PPT Mirror Wills
Specialised Wills that can place the first owner’s share into trust on death for chosen beneficiaries while giving the survivor rights defined by the trust.
2. Severance of Tenancy
Legal transition from Joint Tenants to Tenants in Common, ensuring each partner has a distinct share to place into trust.
3. Health & Welfare LPA
A Health & Welfare LPA can authorise chosen attorneys to make specified personal-welfare decisions when the donor lacks capacity, subject to the Mental Capacity Act, the LPA terms and the decision involved.
4. Finance & Property LPA
A Property & Financial Affairs LPA can authorise chosen attorneys to manage specified financial matters, subject to the LPA terms. Without an appropriate LPA after capacity is lost, a Court of Protection application may be required in some circumstances.
Secure Your 2026 Assessment Review*Book today to receive a comprehensive review of your current deeds and a personal liability audit.*
Tell us what you want to achieve
You do not need to know the name of the legal document or trust before speaking to us. Explain the family, property or planning issue and we can discuss the relevant options.